Why track cash flow in budget: Insight into wealth
"A budget tracks what you spend, but a financial flow record tells you where you are going."
To gain true insight into your wealth, you must look beyond simple expense logging and begin to track cash flow in budget management. This process involves reconciling your monthly spending with long-term stability goals such as debt reduction and emergency savings.
Key takeaways include prioritizing high-interest debt elimination, building a tiered emergency fund, and adjusting the 50/30/20 rule to fit your specific living costs.
How to track cash flow in budget management?
Late at night, I sit at my desk and use a pen to track every movement of money through my ledger.
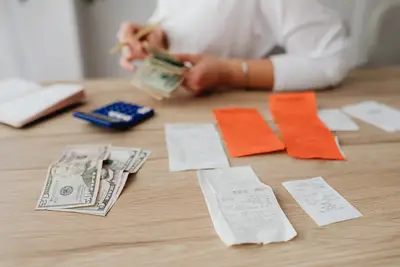
Sitting at a wooden desk with a laptop open, one might realize that a list of grocery receipts does not reveal the health of a household. A standard budget often misses the movement of capital between savings, debt, and investments.
To move from simple tracking to real insight, you must focus on the velocity and direction of your money.
Effective financial flow record keeping requires looking at how much of your income remains after all obligations are met. Instead of just noting a $50 purchase, you assess how that purchase affects your ability to hit a specific target.
This shift in perspective turns a static list of costs into a dynamic roadmap for asset growth.
- Identify all sources of incoming revenue.
- Categorize all outgoing expenses.
- Calculate the net difference between inflows and outflows.
What are the best methods for financial flow record keeping?
At midnight, I grip my pen tightly while I scan the ledger to track every fluctuating cent.
A person might stare at a spreadsheet, wondering why their net worth remains stagnant despite following a strict spending plan. This often happens because the budget focuses on outflows while ignoring the movement of assets.
Understanding the relationship between current spending and future security is the core of advanced analysis.
One approach is to apply the 50/30/20 rule, where 50% of income goes to needs, 30% to wants, and 20% to savings. In high-cost areas, this might shift to a 70/20/10 structure to accommodate higher living expenses.
This provides a baseline to see if your current lifestyle is draining your ability to build wealth.
| Method | Primary Focus | Purpose |
|---|---|---|
| 50/30/20 Rule | Needs/Wants/Savings | Establishing a baseline |
| 70/20/10 Rule | High-cost living adjustment | Managing expensive regions |
I once looked at my own monthly breakdown and realized my "wants" were cannibalizing my ability to reach my savings goals.
In this sequence, the second step is the most time-consuming.
How do you implement an asset management flow log?
Walking through a bank to deposit a check, a person realizes that wealth is built through intentionality rather than just surplus. An asset management flow log tracks how much of your income is diverted into growth-oriented vehicles. This ensures that your money is working as hard as you are.
To implement this, follow these three steps:
- Identify and eliminate high-interest consumer debt, such as credit cards, to aim for a debt-to-income ratio under 10%. 2. Build an emergency fund covering 3–6 months of essential expenses in a high-interest savings account. 3. Automate voluntary contributions to retirement accounts or investment funds to ensure consistent growth.
Always perform a final check to ensure that "wants" are not encroaching on the funds reserved for debt repayment or emergency needs.
How can you achieve gaining insight from spending?
Reviewing a bank statement at the end of the month can feel repetitive without a clear objective. True insight comes from seeing how much money is freed up for investment through lifestyle optimization. By cutting non-essentials, you can potentially free up $1,000–$3,000 monthly for long-term goals.
For example, a family of four might find that rent, groceries, and utilities should be capped at 50% of after-tax income. If these needs exceed that limit, the "wants" category must be tightened to protect the savings rate.
This constant recalibration prevents lifestyle creep from stalling financial progress.
How do you manage specific financial goals?
Standing in a bright real estate office, one might think about the difficulty of saving for a large down payment. When you have a specific target, like a 20% home deposit to avoid LVR restrictions, your cash flow must reflect that priority.
A limitation of these strategies is that they are highly dependent on an individual's specific cost of living and regional economic conditions.
The subject here is Track cash flow in budget.
The same subject is also called Budgeting cash flow tracking.
The same subject is also called Money movement tracking tips.
This part also covers Deep dive into financial flow.
This part also covers Advanced budget analysis methods.
Related
- Fridge cooling tips: Best storage ideas for food
- Fridge freezer temp setting: Tips for optimal food storage
When does a budget fail to show financial health? A budget fails to show financial health when it concentrates solely on tracking outflows without mapping the movement of capital across different financial buckets. This oversight means a simple budget might show expenses are covered, yet the underlying trajectory toward long-term stability remains unclear. The process demands understanding the direction, not just the amount, of the money leaving your accounts. According to Ahead of Union, expectations are high among salaried employees, middle-class households, and senior citizens ahead of Union Budget 2026–27. According to the City Council, the 2026 budget proposal addresses a long-standing complaint from the council and budget watchdogs by finally including specific necessary elements.
How does adjusting the 50/30/20 rule help budget tracking? Adjusting the 50/30/20 rule allows the budget to reflect the reality of a high-cost living situation. When expenses are high, shifting the allocation, for instance to a 70/20/10 structure, provides a necessary comparison point. This comparison reveals whether the current lifestyle is sustainable while still allowing progress toward wealth accumulation.
When reviewing your budget, remember that the goal is not merely to track what you spend, but to direct where your money is going. This proactive approach transforms the static nature of a simple budget into a dynamic tool for financial navigation.
The implementation of an asset management flow log serves as a more advanced form of budget tracking because it mandates intentionality in every financial action.
This log ensures that the surplus identified in the budget is actively channeled toward growth objectives rather than being absorbed by discretionary spending.
Caution must always be exercised when implementing these flow tracking methods; the success of the budget relies heavily on the accuracy of the initial data input regarding your specific living costs.

Comments 0