Debt management with ledger: How to find surplus funds
"Managing debt requires more than just math; it requires a disciplined way to track every single cent flowing through your household."
Debt management with ledger involves tracking income, expenses, and repayment progress to maintain financial stability. This guide provides five practical rules for using a ledger to control debt, covers budgeting for debt control, and offers a method for expense analysis for debt.
How do I start debt management with a ledger?
At the wooden desk, I grip a pen and scribble the first entry of the month into my ledger to face my mounting debt.
A person sits at a wooden desk, opening a clean notebook to write down the first entry of the month. They carefully list each source of income to establish a baseline for what is available to pay down liabilities.
According to the City Council, the 2026 budget proposal addresses a long-standing complaint from City Council and budget watchdogs by including specific measures.
According to Ahead of Union, expectations are high among salaried employees, middle-class households, and senior citizens ahead of Union Budget 2026–27.
Effective debt management with ledger begins with a clear snapshot of current assets and liabilities. You must record every recurring payment and interest rate to see the true scale of your obligations. According to ECOS, the household loan delinquency rate stood at 0.45% as of August 2026.
This low rate suggests that while many are managing, staying ahead of interest is critical for stability.
- List every individual debt with its total balance and interest rate.
- Categorize expenses into fixed and variable costs.
- Allocate surplus funds toward the highest-interest debt.
What are the five rules for debt tracking?
Late at night in the quiet study, I circle the rising total in my notebook, feeling the heavy weight of my debt.
A hand holds a pen, circling a specific number in a column labeled "Total Debt." The goal is to move from vague estimates to precise, actionable figures that reflect reality.
To ensure success, you should follow these five principles: 1. Record every transaction immediately to prevent leaks. 2. Categorize expenses into fixed and variable to find surplus funds. 3. Track interest rates separately to prioritize high-cost debt. 4.
Update the balance weekly to monitor progress against goals. 5. Reconcile the ledger with bank statements to ensure accuracy.
A structured approach to budgeting for debt control prevents the common mistake of overestimating available cash. By maintaining a rigorous log, you turn abstract numbers into a roadmap for freedom.
In this sequence, the second step is the most time-consuming.
How can I perform effective expense analysis for debt?
A person compares a printed bank statement against their handwritten ledger, looking for discrepancies in spending. They mark a small red circle around an unnecessary subscription that was forgotten.
Effective expense analysis for debt requires comparing your actual spending against your intended budget. You must look for "leakage," where small, daily purchases accumulate into significant monthly sums.
Using a financial ledger debt rules framework, you can identify which variable costs can be diverted toward principal payments.
| Category | Purpose |
|---|---|
| Fixed Expenses | Essential payments like rent or insurance |
| Variable Expenses | Discretionary spending that can be cut |
I once spent an entire evening comparing my monthly receipts to my ledger to find where my surplus disappeared. This process of tracking debt with a spending log revealed exactly how much extra could be sent to creditors each month.
How do I apply these rules to an existing condition?
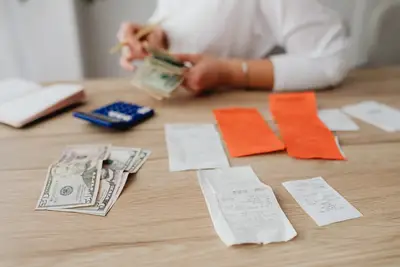
A person looks at a pile of various bills on the table, deciding which one to pay first. They use a calculator to determine the impact of an extra payment on the total balance.
If you already have significant debt, follow these steps to integrate the ledger into your life: 1. List all outstanding balances, interest rates, and minimum payments. 2. Allocate any surplus income from your monthly budget to the highest-interest debt. 3.
Document the reduction in total balance every time a payment is made. 4. Perform a final check to ensure your manual entries match your bank's reality.
This method works for those managing existing financial pressure by providing a sense of control. Applying these techniques helps transform a chaotic situation into a structured plan of action.
What are the limitations of this method?
A person closes the ledger and sighs, realizing that a sudden medical bill has changed the entire budget. The reality of unexpected costs makes the previous month's plan obsolete.
A limitation of this method is that a ledger only tracks recorded data and cannot account for sudden, unrecorded emergencies. For instance, a sudden loss of income or an unexpected large expense can disrupt a planned repayment schedule.
While the ledger provides a roadmap, it remains a reflection of past and current data, not a guarantee against future volatility.
Related
- Electricity usage trends guide Save electricity with budget
- Budgeting to save electricity bills: Tips for lower costs
How does disciplined tracking affect managing debt? Disciplined tracking ensures that the effort put into managing debt translates into tangible progress. When you meticulously record every transaction, you gain insight into spending habits that might otherwise remain hidden. This detailed record allows for adjustments to the repayment strategy when financial circumstances change.
This consistent monitoring is crucial because small, unaddressed expenses can undermine the entire strategy for managing debt. By regularly reviewing the ledger, one can catch spending patterns that deviate from the established budget before they become substantial liabilities.
Maintaining this discipline transforms the abstract concept of financial control into a concrete, observable reality within the ledger.
Comments 0